SOS Restoration Santa Ana assembles the proof a claim runs on, and then you file it. The carrier rules on what your policy pays, not us. Our job is the record behind it. Reading the loss is free. Call (949) 522-4470.
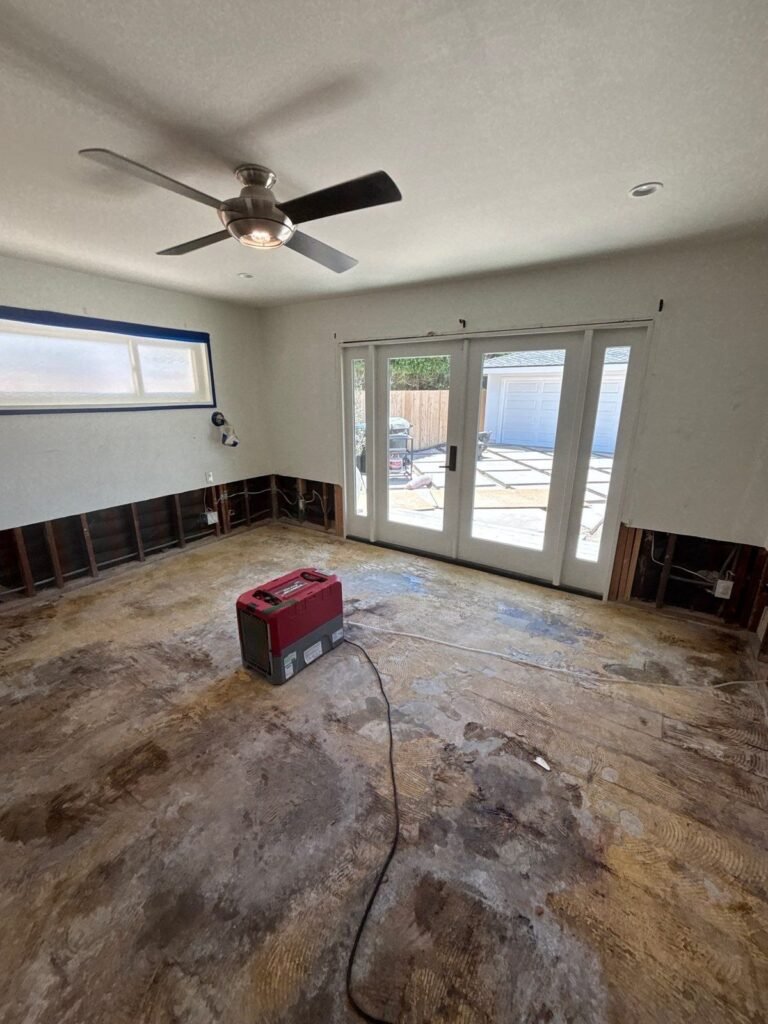
The source, the water, and the mark it left on the wall.
Shoot everything before it moves. To the photos we add dated moisture readings and an itemized list of what came out. The file then shows the damage itself, not just the fix.
You or the insurer first?
Us. Holding the loss down is your duty under the policy.
The fine print asks you to keep damage from spreading, which means drying. We start documenting the moment we arrive, so when you file, the folder already reads clean.
RCV or ACV, what is the difference?
One pays to replace; the other subtracts wear first.
Replacement cost value covers a full replacement; actual cash value knocks off depreciation. A guide on a deductible over the damage shows when a claim is not worth opening.
Insurance Code 2051.5 forbids a window shorter than 12 months to collect the rest.
A condo pipe burst. Whose is it?
Usually the wall decides, and two policies overlap.
Condo rules often give the association the pipe in the shared wall while your policy covers the interior. A guide on a burst condo pipe maps who tends to pay.
Is all water covered?
Sudden, accidental water usually; a slow leak often not.
A pipe that bursts is typically paid; a drip running for months may be denied. Flood from outdoors needs its own policy. We record it either way and leave the ruling to the carrier.
When should you not file?
When the repair costs less than the deductible. Filing then pays nothing and marks the file.
We will read the damage and put a number on it without a claim attached, so the choice is yours with the figure already in hand.
Who talks to the adjuster?
You do, with our moisture log, photos and written scope in hand.
A public adjuster or your own carrier’s adjuster reads that file. We do not negotiate the claim, and any company that offers to is selling something else.
And what does this cost?
The visit is free; drying prices live on the card.
Coming to read the loss carries no charge. The hourly figures sit on the rate card. The dispatcher can say what your policy will likely want.
Not a good moment to talk? Write it down and we call you.
A phone number is all we actually need. Anything else you tell us only decides which crew and which gear leave the shop.
A water claim stands on its record, so we build that first, before a thing is moved.